Djellal Djouad
Financial markets professional and independent researcher in quantitative finance. Co-founder of CrossVol. Signed, first-person notes from the desk on volatility, dealer positioning and cross-asset flow.
ORCIDGoogle Scholar profileSSRN author pageRePEc / IDEAS profileAmazon author page
Latest notesAll notes by Djellal Djouad →
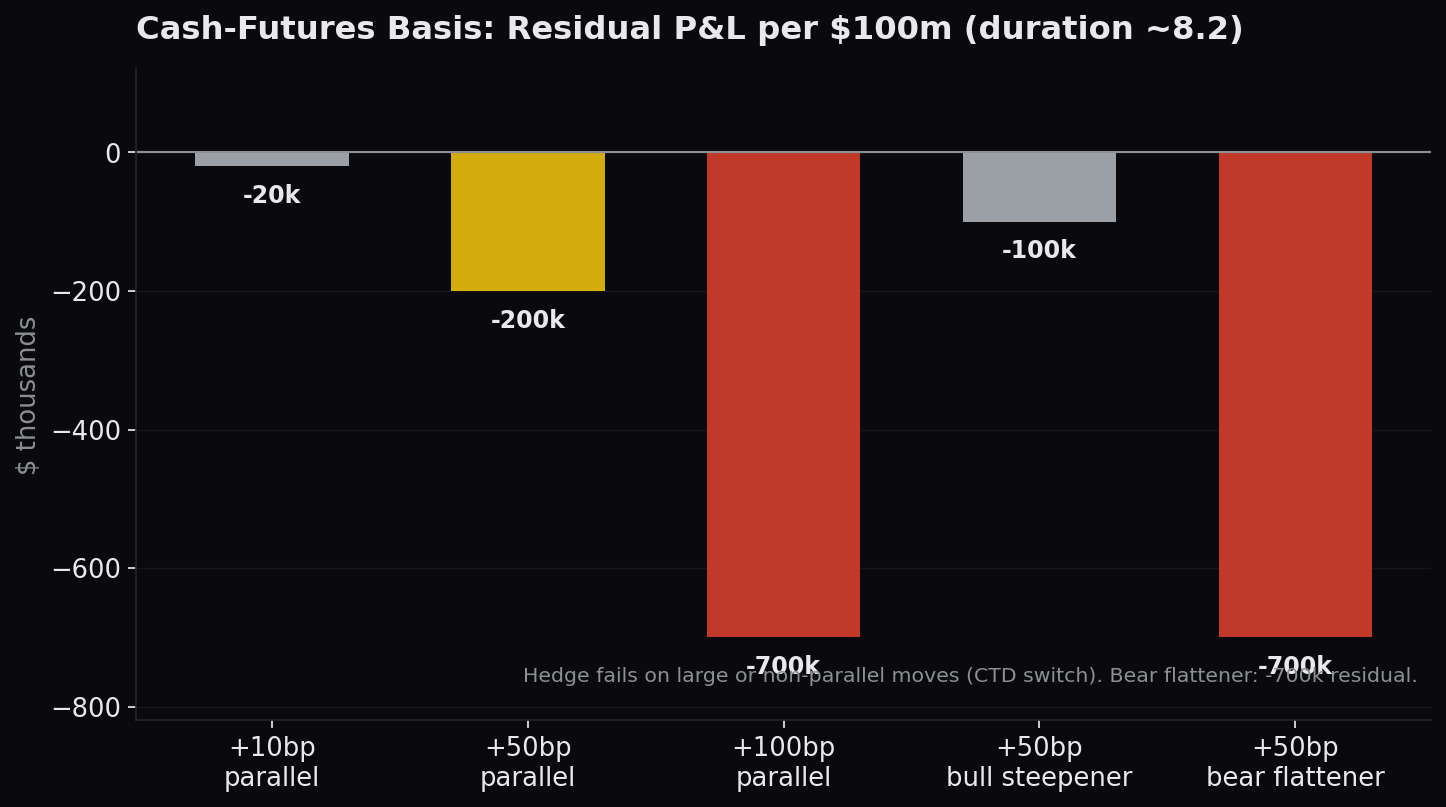
basis trade
The Treasury Basis Trade: Mechanics, Current Stress, and the Shared Tail
A desk-level walk through the cash-futures, repo, curve, and breakeven structures, the point-value math that decides who survives a 50bp day, and the tail the basis book shares with dispersion.
2026-09-19
credit
The Vehicle Beside the Balance Sheet: Broadcom, Hyperscaler CDS, and the 60 Billion Dollar Question
2026-08-22
macro
Same Symptoms, Different Disease: why 2026 is not a rerun of 2022
2026-08-20
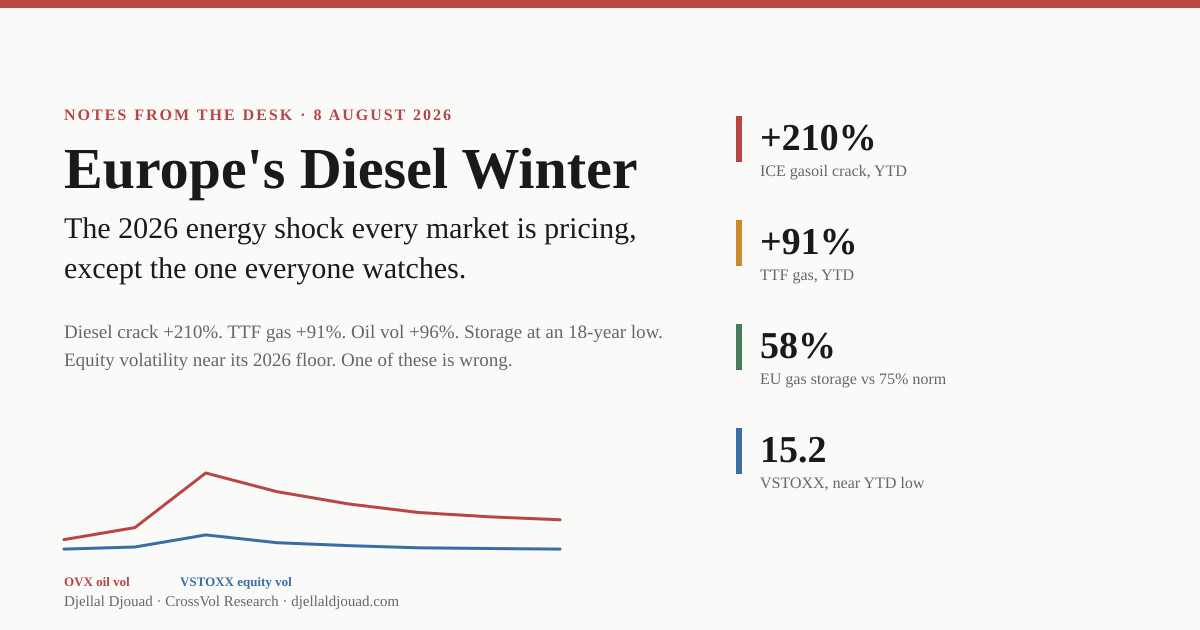
diesel
Europe's Diesel Winter: the 2026 energy shock every market is pricing except equities
2026-08-08
Brent
Brent
The Complex Voted: Brent Cracked 100 and Every Desk Called It a Spike
2026-07-25
Books
The Coming Shadow Banking Crash: Inside the $3 Trillion Ticking Bomb A financial thriller built on real data: four fault lines converging beneath the $3 trillion private credit market.
2026 Beyond Gamma Exposure: A Four-Lens Framework for Options Traders Who See What GEX Misses A four-lens framework for options traders who see what standard GEX misses. · CrossVol Research, Book 1 of 3
2026 FX Traders vs Brokers: Vanilla and Exotic Options, Forwards, and Other OTC Structures: What Retail Traders Never See Vanilla and exotic options, forwards, and the OTC structures retail traders never see. · CrossVol Research, Book 2 of 3
2026 The China AI Disruption Thesis: Why The Sell-Side Is Six Months Late On AI Infrastructure Why the sell side is six months late on AI infrastructure. · CrossVol Research, Book 3 of 3
2026 CrossVol Research Series of three books on Amazon.
SeriesWorking papers
All working papers by Djellal Djouad →
Research & elsewhere
The Crash Fuse Is Lit: Oracle, Bessent, the Yen and Quarter EndOracle's force majeure, a 237 bp CDS, SoftBank's ARM margin loan, Japanese repatriation and Bessent's strong yen push all meet at the September 30 quarter end.
All research notes in the CrossVol Research newsletter51 signed notes, newest first
51 notesCrossVol Research newsletterWeekly volatility and positioning reads
weeklyCrossVol Research on note.comThe same desk research in Japanese
JP